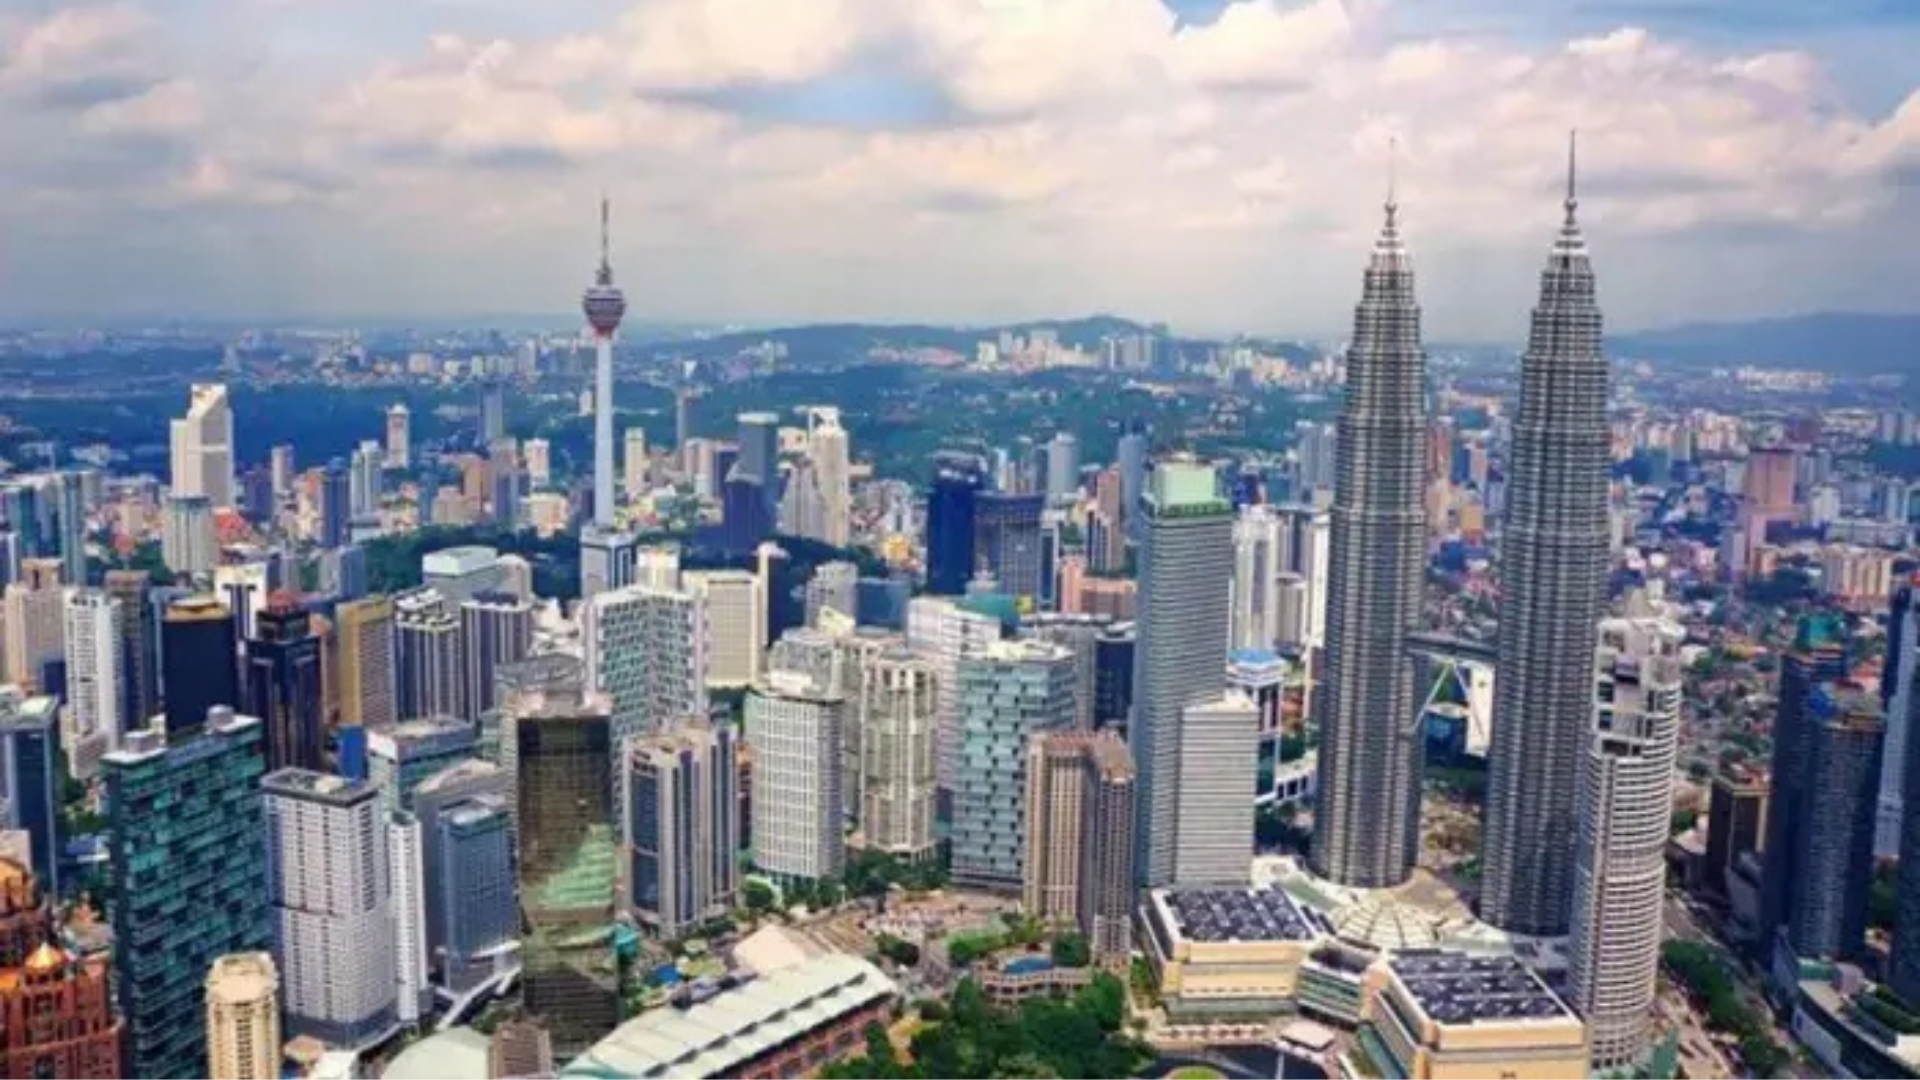
KUALA LUMPUR, AUGUST 2026 — Malaysia’s economy is expected to grow at a slower pace during the second half of 2026, although economists say the moderation should not be interpreted as a broad deterioration in the country’s economic fundamentals.
The expected slowdown follows an exceptionally strong first half, when Malaysia recorded 5.7% GDP growth. The economy expanded 6.0% year-on-year in the second quarter, accelerating from 5.4% in the first quarter and surpassing the earlier advance estimate of 5.8%.

Bank Negara Malaysia’s latest quarterly assessment also showed that the economy expanded by 2.5% quarter-on-quarter on a seasonally adjusted basis in the April-to-June period, supported by resilient domestic activity and stronger exports.
TA Research expects Malaysia’s full-year GDP to expand by 5.1% in 2026, only slightly below the 5.2% growth recorded in 2025. Its projection assumes economic growth will moderate to around 4.6% in the second half of the year following the strong first-half performance.
The research house said less favourable base effects would mechanically reduce headline growth rates, but underlying economic activity should remain healthy.
Domestic consumption, continuing expansion in services and manufacturing, tourism activity and ongoing investment projects are expected to provide support during the remaining months of 2026.
TA Research identified geopolitical developments, global demand conditions and inflationary pressures as key risks that could influence Malaysia’s growth outlook.
Manufacturing is expected to remain one of Malaysia’s most important economic engines during the second half, although the pace of expansion is likely to normalise after its strong performance earlier in the year.
TA Research pointed to Malaysia’s purchasing managers’ index remaining above the 50-point threshold, while sustained demand for semiconductors should continue benefiting export-oriented manufacturers.
Malaysia has also benefited from the ongoing global technology and artificial-intelligence investment cycle. Bank Negara Malaysia noted that strong electrical and electronics exports have been driven primarily by semiconductors and related equipment, reflecting firm external demand connected to the global AI cycle.
July export figures will provide another important indication of whether that momentum has continued. Malaysia’s July trade data is scheduled for release on August 20, according to the report.
Construction is another sector expected to remain supportive, helped by ongoing infrastructure, non-residential development and investment-related projects.
Although construction growth could moderate from the stronger rates seen in the first half, Malaysia continues to attract investment into sectors including manufacturing, technology, data centres and infrastructure.
This combination of household spending and investment has helped cushion the economy against uncertainty in external markets. Bank Negara Malaysia’s second-quarter assessment said sustained domestic demand and stronger exports remained central to Malaysia’s recent economic resilience.
Apex Securities Research is also expecting a slowdown.
Its full-year GDP forecast stands at 5.0%, implying economic growth of approximately 4.4% during the second half of 2026. The research firm said the slowdown would partly reflect the high comparison base created by strong economic growth during the second half of 2025.
However, Apex Securities warned that the economic impact of continued tensions in the Middle East could become more visible over the coming months.
Rather than focusing only on the risk of supply disruptions, businesses may increasingly face persistent cost pressures, which could affect production and investment decisions.
Higher input costs have already become more evident.
Malaysia’s Producer Price Index increased 9.2% year-on-year in June 2026, accelerating from 7.8% in May and marking a significant rise in upstream production costs.
The mining sector recorded the strongest increase at 29.0%, while agriculture, forestry and fishing prices rose 9.1%. Manufacturing producer prices were also higher during the month.
Apex Securities said companies have generally been able to reduce supply-chain disruption risks by sourcing from alternative suppliers, but doing so can involve higher prices. Those additional costs could become a more significant economic headwind if geopolitical uncertainty remains prolonged.
Another factor that could moderate growth is the gradual unwinding of earlier inventory-building and front-loading activities.
Apex Securities noted that Malaysia’s July manufacturing PMI showed purchasing activity was broadly flat despite stronger new orders, suggesting that companies may be moving away from the earlier period of aggressive inventory accumulation.
This could produce a softer headline manufacturing growth rate even if underlying demand remains relatively healthy.
For economists, the distinction is important: slower growth in the second half does not necessarily mean economic activity is contracting, but rather that the pace is normalising after an unusually strong beginning to 2026.
Phillip Capital Research is taking a somewhat more positive view than several of its peers.
The research house said Malaysia’s domestic economy had demonstrated greater resilience than expected despite persistent uncertainty in the global environment.
Stronger-than-anticipated manufacturing and external trade performance, together with resilient domestic demand, have shifted the balance of risks to its GDP forecast towards the upside.
That view is consistent with official data showing the economy maintained solid momentum in the second quarter despite external challenges. Bank Negara Malaysia currently reports real GDP growth of 6.0% for Q2 2026, while consumer inflation stood at 1.9% year-on-year in June.
The overall consensus suggests Malaysia is entering a period of slower but still healthy economic expansion.
Forecasts of around 4.4% to 4.6% growth in the second half would represent a significant moderation from the 5.7% first-half pace, but would still indicate continued expansion across the economy.
Domestic demand, infrastructure investment, tourism, semiconductor exports and the broader technology cycle are expected to remain important growth pillars, while inflationary pressures, geopolitical tensions and weaker global demand represent the main downside risks.
The next major indicators — including July trade figures and subsequent manufacturing data — will help determine whether Malaysia can maintain enough momentum to meet or potentially exceed economists’ full-year GDP forecasts.